Chapter 63 — Income tax
Where income tax is collected through payroll, the employer is the tax authority's agent: it works out each month's tax, withholds it, reports it, and gives every employee a statement of what was withheld. Getting it wrong is the employer's problem first. This chapter covers how Operentra withholds, the brackets it withholds from, the corrections HR can record, and the certificate at the end of the year. A workspace in a country with no income tax on salaries does not see any of it: the whole Tax section is absent there.
This chapter applies to workspaces in countries that levy income tax through payroll.
What this chapter covers
- 63.1 When tax applies (the tax component)
- 63.2 Tax brackets per fiscal year
- 63.3 Tax adjustments: credits and debits
- 63.4 Tax certificates: admin and employee
- 63.5 Tax certificate templates
The concept
Withholding is an estimate made every month of a liability settled once a year. The usual method is to annualise: treat this month's taxable pay as if it were earned all year, work out the year's tax on that from the brackets, and withhold a twelfth. It is simple, it adjusts at once when pay changes, and it is not exact: the year's real tax is settled when the employee files, and any difference is theirs to pay or reclaim. Two things the employer must get right are the brackets for the year, which change with each budget, and the statement at the end, which the employee files from.
How Operentra handles it
- Tax applies to an employee whose salary structure includes the
TAXcomponent (Chapter 51); a structure without it is tax-free by design. The country pack decides the method: brackets, a flat rate, or none. - Each month the run annualises the month's taxable pay (taxable earnings after exemptions, less docked days, plus taxable additions and, where bonuses are wages, bonuses), applies the year's brackets and withholds a twelfth. Year-to-date figures are recorded but do not change the month's withholding.
- Tax › Tax Slabs holds the brackets per fiscal year.
- Tax › Adjustments records credits and debits that change the tax shown on the year's certificate and tax report, not the withholding.
- Tax › Certificates produces each employee's annual statement; employees download theirs from the portal.
- Who:
payroll.configurefor brackets (Super Admin, HR Manager);payroll.managefor adjustments and templates (Super Admin, Accountant);tax.certificatesfor certificates; every employee sees their own (tax.view_own).
Walkthrough
Northwind is a US workspace on one structure, "Standard US (Federal
Withholding)", which carries the TAX component and FICA. Its brackets
for fiscal years 2024, 2025 and 2026 are the federal brackets for a
single filer with the standard deduction folded into a zero-rate first
bracket (16,100 for 2026). State and local income tax are not
withheld, as the structure's description says. It has five tax
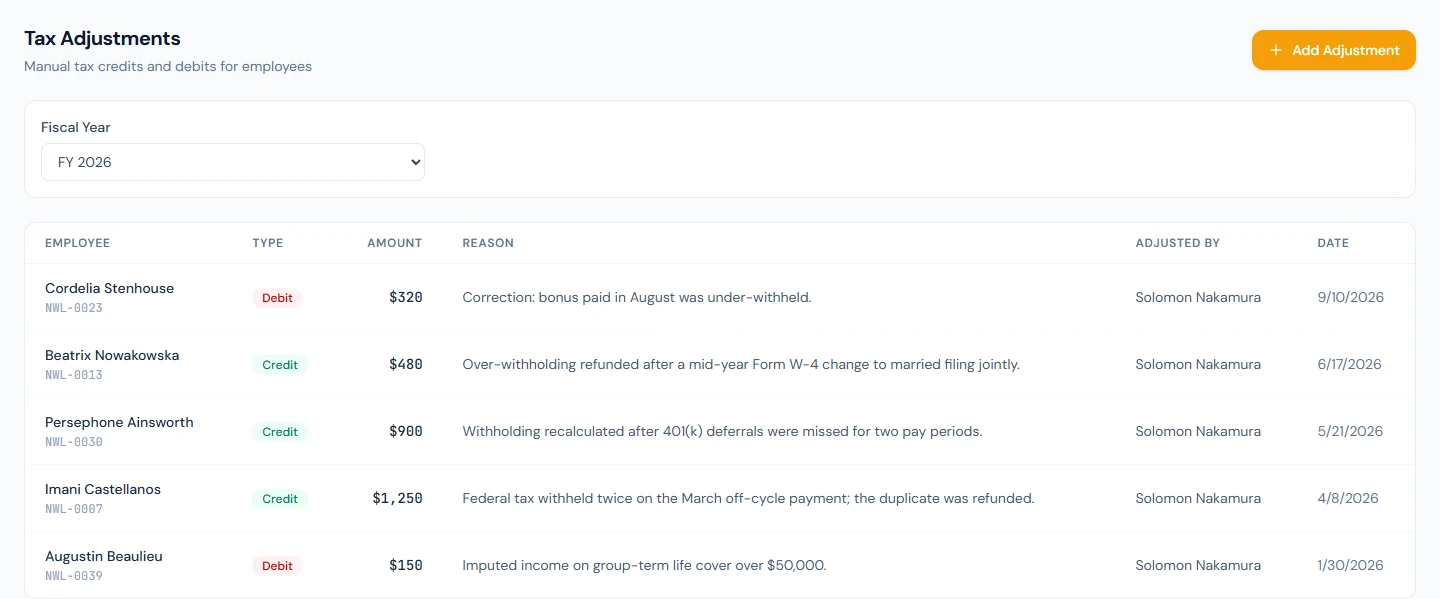
adjustments in 2026, three credits and two debits.
63.1 When tax applies (the tax component)
Three conditions decide whether a payslip has income tax: the
workspace's country levies it through payroll, the year has brackets
(or the country uses a flat rate), and the employee's structure carries
the TAX component. The third is HR's lever: an employee who is
exempt, a director paid outside payroll, someone covered by a treaty,
is put on a structure without TAX and nothing is withheld, by
design. The run's checks refuse approval while a year where tax
applies has no brackets (Chapter 55).
Taxable pay for the month is the taxable earnings after any exemption (Chapter 51), less pay docked for absence and unpaid leave, plus taxable adjustments and, in US, UK and Canadian workspaces, bonuses (Chapter 56). The run annualises it, applies the brackets and withholds a twelfth; the employee's slip shows the taxable figure and the tax. A raise or a bonus changes that month's withholding at once; nothing is trued up against the year so far, so the annual figure on the certificate is the sum of what each month withheld.
63.2 Tax brackets per fiscal year
Tax › Tax Slabs shows the brackets for the fiscal year chosen at the top. Each row is one bracket of annual taxable income: Income From, Income To, Fixed Tax (the total tax on all income up to Income From) and Rate % (on the part above it, up to Income To). Northwind's 2026 rows read, for example, 66,500 to 121,800 with a fixed tax of 5,800 at 22%: on 90,000 the year's tax is 5,800 plus 22% of 23,500, 10,970, and the month withholds 914.17. Add Row and Save All replace the year's brackets in one go.
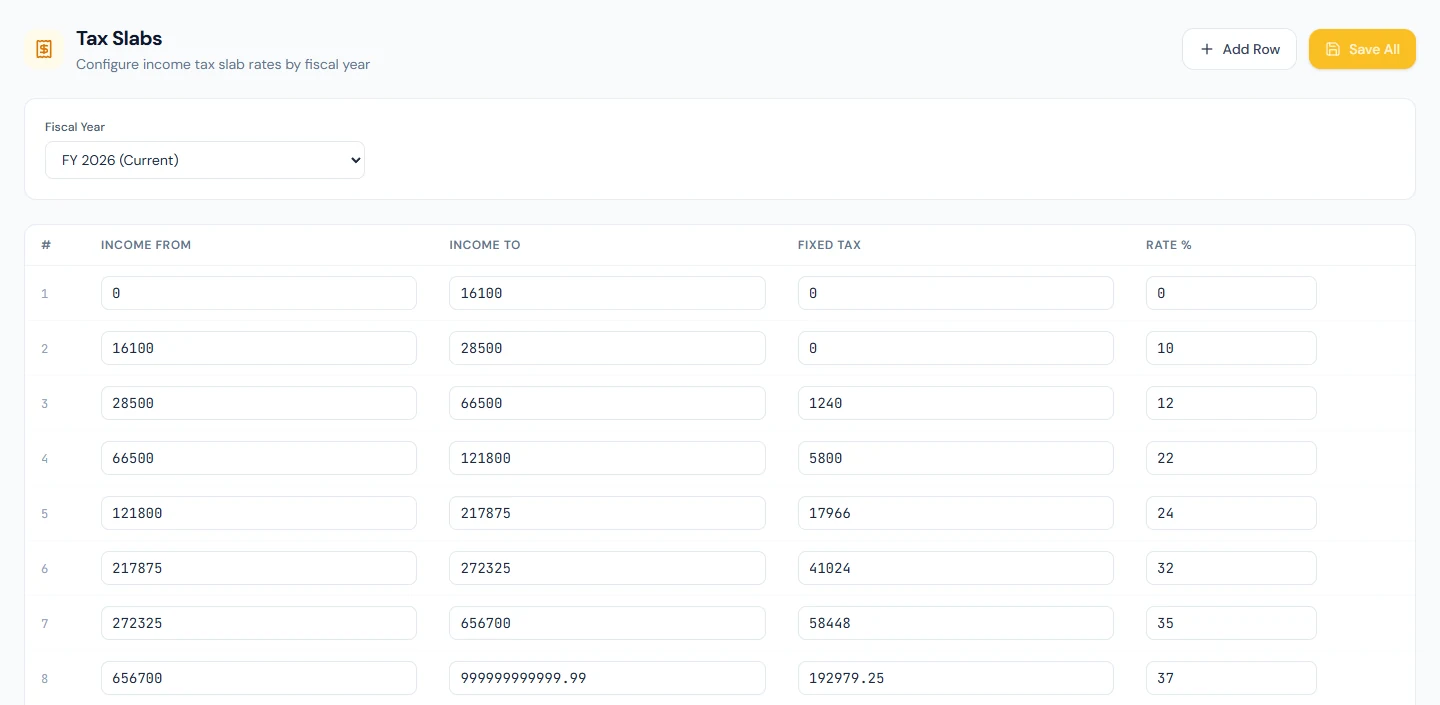
Brackets do not roll forward with the fiscal year (Chapter 10): a new year starts empty unless the country pack ships its figures, and a year with no brackets withholds nothing while the run's checks refuse approval. Enter the new year's brackets as soon as they are published, before the first run of the year.
63.3 Tax adjustments: credits and debits
Tax › Adjustments, for a chosen fiscal year, lists each adjustment with the employee, the type, the amount, the reason and who recorded it. Add Adjustment takes the employee, Credit (reduce tax) or Debit (increase tax), the amount and a reason ("Tax rebate for investment"). An adjustment changes the tax deducted shown for the year, on the certificate and in the tax report; it does not change any payslip or the next month's withholding. Use it to make the year's statement match what was really settled: a rebate granted outside payroll, tax paid on the employee's behalf, a correction of a month that was locked. Imani's 1,250 credit lowers the tax on the 2026 certificate by that amount; the 320 debit for NWL-0023 raises the tax on that certificate by 320.
63.4 Tax certificates: admin and employee
Tax › Certificates lists, for a fiscal year, everyone with payroll in it: months, gross, taxable, tax deducted (with adjustments), and actions to view or download the certificate as a PDF. The certificate is the employee's statement of earnings and tax withheld for the year, month by month, with the adjustments shown. Gross on the list, the certificate and the tax reports is the pay earned, not the contracted salary: every earning line, bonuses and payroll additions, less the days docked for absence, unpaid leave and late arrivals. Expense claims reimbursed through payroll are left out, because they repay the employee's own money. In a US workspace it is a statement for the employee's records, not the W-2, which the employer files and issues through its tax reporting; the figures on both should agree. Employees download their own from Tax Certificates in the portal, for every year they were paid.
63.5 Tax certificate templates
Tax › Templates holds the certificate's design: the system template for the country (a statement of earnings and tax withheld, in the workspace's document language, or a country's own statutory format where one exists), read-only and cloned to edit, and the workspace's own. Add Template takes HTML built from the tokens listed beside the editor (the employee, the year, each month's figures, the totals, the adjustments), with a preview. The workspace's active template is used for every certificate; a country without a template of its own uses the system statement.
What happens next
- Reports (Chapter 65) include the tax report by employee and fiscal year; year-end is checking that the brackets, adjustments and certificates agree with what was filed.
What the employee sees
The taxable pay and the tax on every slip, and their annual tax certificate under Tax Certificates in the portal.
Common mistakes
- A structure without
TAXby accident. Nothing is withheld; the employee owes it all at filing. - Running the first payroll of a new year without its brackets. The checks refuse approval; enter the brackets first.
- Entering brackets as marginal rows only. Fixed Tax must hold the cumulative tax up to Income From, or every bracket after the first is under-taxed.
- Expecting an adjustment to change a payslip. It changes the year's statement; a refund is paid as an adjustment in payroll (Chapter 56).
- Debit and credit the wrong way round. A credit reduces the tax on the certificate; a debit increases it.
- Treating the statement as the government form. File and issue the official form your country requires; the statement should agree with it.
- Withholding state or local tax through the federal brackets. They are not withheld; handle them separately or with their own arrangement.
Practice
Use your own trial workspace, not a customer's, in a country with income tax.
- Open Tax › Tax Slabs for the current year and work one month's tax by hand for a salary of your choice; compare it with a processed slip.
- Move a throwaway employee to a structure without
TAX, reprocess the month, and read the slip. - Add a credit and a debit for two employees and read their certificates.
- Download a certificate as PDF, then sign in as the employee and download it from the portal.
- Clone the certificate template and preview it.
Quiz
1. What three conditions put income tax on a payslip?
The country levies it through payroll, the year has brackets (or a flat
rate), and the employee's structure carries the TAX component.
2. How is a month's withholding worked out?
The month's taxable pay is annualised, the year's brackets are applied, and a twelfth is withheld; nothing is trued up against the year so far.
3. What does Fixed Tax mean on a bracket row?
The total tax on all income up to Income From; the rate applies to the part above it.
4. What does a tax adjustment change?
The tax deducted shown for the year on the certificate and the tax report; not any payslip or withholding.
5. Where do employees get their certificate?
From Tax Certificates in the portal, for every year they were paid.